 Search


- Single quarter business performance hits historic best
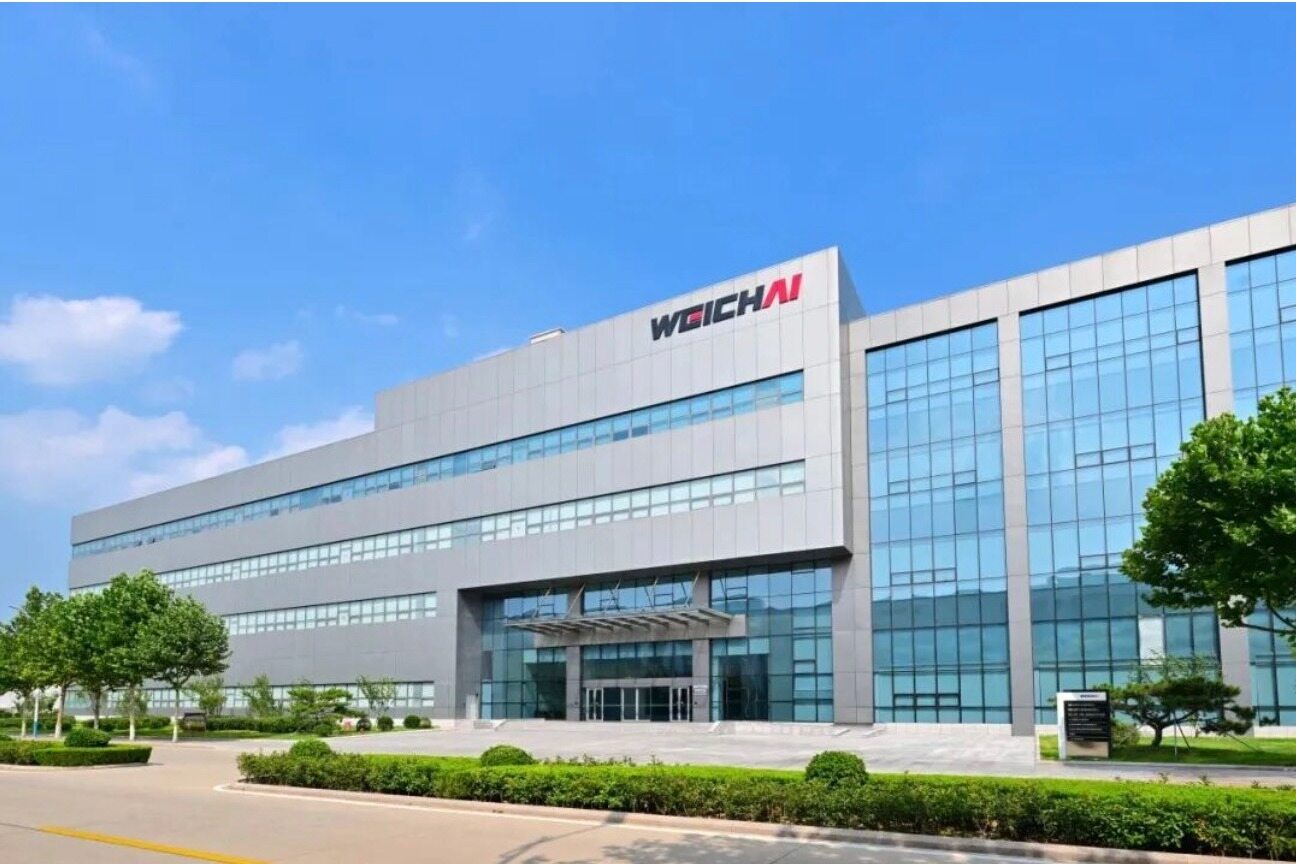
Faced with the complex environment of structural changes and increasing internal and external uncertainties in the commercial vehicle industry, Weichai has demonstrated strong operational resilience with its deep accumulation of traditional power business. Strategic emerging businesses such as electric power energy and new energy continue to break through and increase in volume, accelerating its transition to a multi engine driven growth equipment enterprise and delivering an unexpected third quarter performance report.
On the evening of October 29th, Weichai disclosed its third quarter report for 2026. In the first three quarters, the company achieved a revenue of 181.17 billion yuan, a year-on-year increase of 6.2%; The net profit attributable to the parent company was 10.66 billion yuan, a year-on-year increase of 20.1%. The single quarter performance was even more impressive, achieving a revenue of 58.01 billion yuan and a net profit attributable to the parent company of 2.96 billion yuan in the third quarter. Deducting non recurring net profit of 3.22 billion yuan, setting a new historical high for a single quarter, with a year-on-year increase of 13.9% and a month on month increase of 2.8%. The quality of profits and growth momentum are synchronously improving.
The power system has built a solid foundation for the company's performance, and its business structure is undergoing profound changes. In 2026, due to geopolitical factors and rising oil and gas prices, the demand for natural gas heavy-duty trucks will weaken in stages, and the penetration rate of the track will decline; In sharp contrast, the industrialization of new energy heavy-duty trucks has accelerated, and the industry penetration rate in the third quarter has approached 50%.
Relying on a multi technology route layout and a complete production capacity supporting system, Weichai Power flexibly adapts to the pace of structural changes in the industry and continues to promote the transformation of its new energy strategy. In the first three quarters, the company's sales of power batteries reached 9.3 GWh, a year-on-year increase of over 140%, with a revenue of 4.85 billion yuan; The new energy power system business maintains high-speed growth and gradually grows into a new growth engine for the power system sector.
The growth logic that Weichai deserves continuous attention at present lies in the fact that the power energy business has moved beyond the conceptual narrative and become a deterministic growth curve for Weichai Power. The global AI computing infrastructure boom is in full swing, and the International Energy Agency (IEA) estimates that the electricity consumption of global AI data centers will triple by 2030 compared to 2025. The long construction cycle of the power grid and the fast deployment pace of servers result in a significant mismatch between the two, creating a structural gap between computing power expansion and power supply, forcing AIDC projects to shift from relying on public power grids to self built power sources. Self owned generator sets have become the main solution for data centers to be put into operation on schedule. Fast delivery and flexible deployment of gas internal combustion engines have become the core choice for peak shaving and even base load power supply.
With long-term technological accumulation and delivery cycle advantages in the field of large bore power, Weichai Power quickly entered the high prosperity track of AIDC power supply and built differentiated competitive barriers. In the first three quarters, the company sold over 11000 high value-added M-series large bore engines, a year-on-year increase of over 40%; Among them, the diesel engine products in the data center continued their high growth trend, with sales exceeding 2700 units in the first three quarters, a year-on-year increase of nearly 200%. Not only that, Weichai Power also has a forward-looking layout for new energy solutions such as SOFC solid oxide fuel cells, and multiple demonstration projects have been put into operation. The technological maturity and commercialization potential have been verified, laying the foundation for subsequent large-scale industrialization.
The performance continues to be fulfilled, but Weichai's valuation is still in the low range. Industry analysis suggests that the current market has not fully priced the long-term value of the new incremental curve of electricity and energy, and the company's valuation still has room for repair. JPMorgan Chase's latest research report further raised the target price of Weichai Power's A-shares and H-shares, maintaining its "increase in holdings" rating.
Looking ahead to the future, Weichai will deepen its traditional diversified power base, expand its business scope in electric energy and new energy, and continue to broaden its growth boundaries. With the continuous increase in AIDC power supply and new energy power business, Weichai Power's growth narrative will gradually be validated.Editor/Yangmeiling
Comment

 Praise
 Collect
 Comment

 Share


Write something~